Welcome to the next edition of On The Record, thoughtful analysis on culture, entertainment, tech, fashion, music, sport, and brands. Here's a round-up of key conversations and campaigns that caught my attention this week.
This fortnight, the most powerful position in culture belonged to whoever does the counting. TikTok commissioned Luminate to report that 94% of 2025's global hits went viral on the app first, Netflix Ads built Still Watching 2026 on a survey of 1,125 people in the UK, TikTok Shop published HarperCollins's 225% growth without a base, and OpenAI launched a Business Hub that tells brands how often ChatGPT mentions them, counted by OpenAI. Even the chart has moved to a platform's terms: after ten months of withholding its data, YouTube returns to Billboard in January with a free stream worth two-thirds of a paid one, up from two-fifths. A second thread runs underneath, where demand is strong and the money lands at the top. Glastonbury sold out at a record £408 before naming an act while 45 independent festivals fell in 2026, Spider-Man: Brand New Day and The Odyssey took 56% of the UK and Ireland's August box office, and Gotham FC raised money at a reported record $350m valuation in the same fortnight that Real Madrid Women turned a record €14.4m of revenue into a €785,000 loss. The two threads meet in one place. Where a platform keeps the scorecard, the scorecard tends to favour the platform, and this fortnight it also favoured whoever was already at the top.
🏆 SPORT, POWER & GOVERNANCE
WNBA Explores Buying Back the 16% Stake It Sold for $75m 🏀
📌 Four years after selling a sixth of itself to pay for a marketing overhaul, the women's basketball league wants the equity back, and outgoing commissioner Cathy Engelbert is trying to get it done before she leaves at the end of December. The 2022 raise valued the league at roughly $475m post-money. A single expansion slot now costs more than half that. NBA commissioner Adam Silver has described the talks as an effort to align incentives between stakeholders, which is the polite way of saying the ownership structure no longer suits the league.
16% equity stake sold for $75m in February 2022, an implied post-money valuation of around $475m
League equity now split 42% NBA team owners, 42% WNBA team owners and 16% held by the 2022 investor group
Cleveland, Detroit and Philadelphia each paid a reported record $250m expansion fee, more than three times what investors paid for the entire 16%
💡 Several of the 2022 buyers already owned NBA or WNBA teams, so the Tsais, Ted Leonsis and Herb Simon hold the same league from three sides of the table. That means some of the sellers in any buyback also vote on the price. That is the misalignment Silver is pointing at, and it explains why the obvious fix is so expensive: the league would pay a 2026 price to undo a decision it made in 2022, when it was short of cash and had little bargaining power. The party missing from the conversation is the players. A 16% equity claim held by passive investors is value they can't bargain over, after a full CBA cycle spent fighting for a bigger share. Engelbert's successor inherits a league that sold part of its upside early, and how that gets cleared up will be the first sign of whether the next commissioner works for the W or for the people who own pieces of it. 🧾
Gotham FC Raises $100m at a Record $350m Valuation for a Women's Football Club 🗽
📌 Women's football has a new price ceiling. Gotham FC, NWSL champions in 2023 and 2025, have raised $100m from seven new minority investors plus existing backers, at a valuation reported to be $350m, the highest yet for a women's football team. Carolyn Tisch Blodgett's Next 3 keeps majority control. The money goes on players, a new training base in Whippany, New Jersey, and the club's move into New York City FC's Etihad Park in Queens in 2028.
$100m raised at a reported $350m valuation, an 84% premium on Forbes' $190m estimate in April
Sportico's March 2026 rankings put Angel City top of the NWSL at $335m
From 2028, Gotham becomes a permanent tenant at NYCFC's 25,000-seat Etihad Park
💡 Ownership is the part of this story worth watching. Investors bought into Gotham at a $40m valuation in 2022, and the same club is now priced almost nine times higher. For scale, the WNBA sold 16% of its whole league that same year at an implied $475m. Gotham's new training base will be its own, but from 2028 its stadium will belong to NYCFC, and that split decides how much of the next rise in value Gotham keeps. Kansas City Current built its own stadium and keeps the matchday, hospitality and naming revenue on its own books. Gotham has traded control for reach, a 25,000-seat venue in the middle of New York with a far bigger catchment than Harrison. That's the right trade while the brand is still growing, and the five-year lease lets the club revisit owning a venue once it knows what the New York audience is worth. 🗽
Everton Women Sign Two Partners in a Fortnight, and Goodison Is What They're Selling 🍫
📌 A year after moving into Goodison Park, Everton's women's team is turning the old ground into commercial inventory. Nestlé Confectionery has signed a multi-year deal as official chocolate and grab-bag sweet partner. It gets LED, big-screen and matchday activation rights at Goodison, and official supplier status at Hill Dickinson Stadium, the men's ground. Danish retailer JYSK signed within a fortnight, giving the women's side three standalone partners.
Nestlé is only the second dedicated commercial partner for Everton Women, after catering equipment firm GGM Gastro last year, and most of the club's other sponsorships still cover the men's team
JYSK became the third dedicated partner on 16 November and will furnish spaces for players, staff and supporters at Goodison
Everton Women moved to Goodison from Walton Hall Park, which held 2,200, and their first WSL match there drew 6,473
💡 Look at what Nestlé actually gets. The deal is badged as a women's team partnership, yet it also makes Nestlé an official supplier at the 52,000-seat men's stadium, so the women's side has become the route into the club's biggest confectionery estate. All three of Everton Women's partners hold category deals: catering kit, chocolate and furniture. That's the inventory a club controls once it runs its own ground, and it's where Goodison changes the arithmetic. LED boards, screens and supply rights belong to the women's club to price, whereas Gotham, for comparison, will be a tenant in NYCFC's building from 2028. The next tier of value, shirt and naming rights, depends on putting more of Goodison's seats on camera with people in them. 📈
Real Madrid Women Hit Record €14.4m Revenue and Return to a €785,000 Loss ⚽
📌 A loss planned eight months in advance reads differently from one that arrives by surprise. Real Madrid's women's team grew revenue by around €2m to a record €14.4m in 2025-26, with sponsorship and merchandise making up more than four-fifths of it, yet swung from a profit in 2024-25 to a €785,000 loss. The club had flagged this back in March, when it chose to push squad spending to a record level instead of banking another surplus.
Revenue €14.4m. Sponsorship and merchandise brought in €11.8m, 82% of the total
Net loss of €785,000 for 2025-26, while the budget for the current season rises to around €16m
The 2026-27 budget projects revenue of €16.2m and a loss of €1.3m
💡 The figure that matters is the 82%. A women's team earning four-fifths of its money from sponsorship and merchandise has built its business on brand partners ahead of gate receipts or broadcast. That's a strength for as long as partners see value in the shirt. That value grows with winning moments, and Madrid are still waiting for theirs against a Barcelona side that beat them 7-0 in October. Spending ahead of revenue is a normal stage in building a women's club, and budgeting for this loss in March shows Real Madrid treating the team as an asset worth investing in. A business this dependent on sponsors needs sporting moments to justify the renewals, and a record squad budget is the right way to go and win them. ⚽
Apple Sports Adds UFC, With Live Fight Stats on the Lock Screen 🥊
📌 Combat sport is the latest live property to get Apple's scoreboard treatment. A free update to the Apple Sports app on 12 November added every UFC card, from early prelims to the main event, with fighter profiles and round-by-round stats including significant strikes, takedowns and control time. Live Activities push updates to the iPhone lock screen and Apple Watch, and the update was timed for UFC 334 at Madison Square Garden on 14 November.
Paramount holds exclusive US rights to UFC under a seven-year, $7.7bn deal that began in 2026. It covers 13 numbered events and 30 Fight Nights a year on Paramount+, and ended pay-per-view
Live stats in Apple Sports include significant strikes, total strikes, takedowns, knockdowns, submission attempts and control time
Apple Sports now comes preinstalled when a new iPhone is set up
💡 The lock screen is the most valuable real estate in live sport, because it's where a fan decides whether to switch on. Apple now holds that spot for UFC without needing the broadcast rights. Paramount paid $7.7bn to put every event on Paramount+, and a strike-by-strike alert landing mid-round is exactly the nudge that sends a casual follower to the stream, so the rights holder gains from Apple's layer as much as Apple does. It's the same discipline as the podcast move in this edition, applied to a different moment: Apple builds the daily habit around live events and leaves the expensive part to the rights market. UFC fans live on clips, stats and group chats, so the shareable fight card is the smart detail, because it makes Apple's interface the place the conversation starts. 🥊
🎶 MUSIC, LIVE & CULTURE
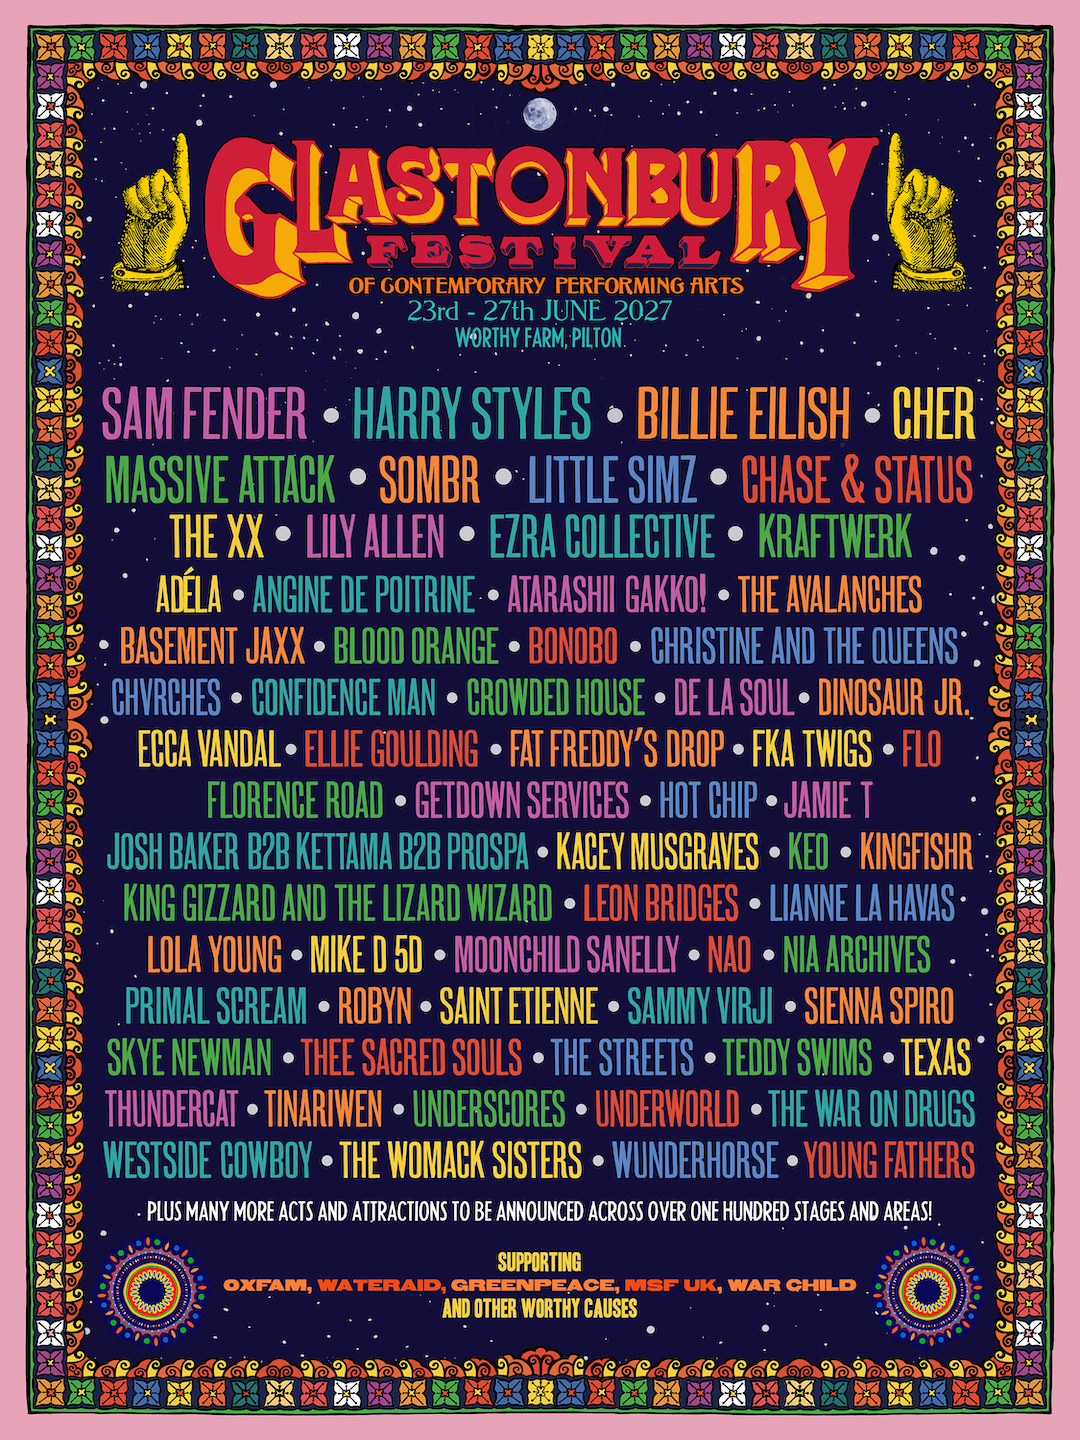
Glastonbury Names Sam Fender, Harry Styles and Billie Eilish as 2027 Headliners, With Cher in the Legends Slot 🎪
📌 A festival that sold out before naming a single act has now revealed its bill seven months early. Glastonbury's first 2027 poster, published on 18 November, puts Sam Fender, Harry Styles and Billie Eilish on the Pyramid Stage and Cher in the Sunday afternoon Legends slot, with Massive Attack, Little Simz, Kraftwerk and The xx high on the undercard. It's the youngest set of headliners the festival has booked this century.
First line-up revealed on 18 November, months earlier than the festival's usual spring announcements
Fender and Styles are 32 and Eilish is 24, making them the youngest Glastonbury headliners of the 21st century
Tickets sold out at a record £408 before any act was confirmed
💡 Glastonbury doesn't need a poster to sell tickets, so this one is doing a different job: it sets the story seven months out, before the rumour market can. The booking is a generational handover. Styles and Cher are both making their festival debuts, and the undercard includes three of this year's Grammy Best New Artist nominees: Sienna Spiro, Angine de Poitrine and The Womack Sisters. Fans calling the headliners "atrocious" sounds like a core audience reading the top line as built for the mass market. The undercard, from Kraftwerk to Atarashii Gakko!, is still built for the overlapping scenes that made the festival. That's the right split for an event that's already sold out: the headliners bring the broadcast audience, and the depth underneath keeps the people who'll buy again for the next edition. 🎪
45 UK Independent Festivals Cancelled, Postponed or Paused in 2026, Two More Than Last Year ⛺
📌 Glastonbury sold out at a record price before naming a single act. Further down the market, a strong summer of ticket sales still wasn't enough. The Association of Independent Festivals counts 45 UK events that cancelled, postponed, paused or closed in 2026, against 43 in 2025 and a record 78 in 2024, and says the cause is production costs and cash flow rather than demand. It's pressing the government for a grassroots festival tax relief modelled on the schemes that already support theatre and orchestras.
45 festivals as of 13 November 2026, a figure that includes postponements and fallow years as well as permanent closures
43 fell in 2025, after a record 78 in 2024
The proposed relief would cover festivals under 30,000 capacity and is modelled on Theatre and Orchestra Tax Relief
💡 The number has stopped falling, and that's the real story. After the sharp drop from 2024's peak, losses have settled at around 45 a year, which looks like a structural floor rather than a bad patch. AIF chief executive John Rostron has named the mechanism: independents now pay for almost everything up front, from staging to artists to toilets, without the ticketing advances that used to bridge the gap, while bigger operators can carry those costs. Every 5,000-capacity weekender that disappears removes a rung on the ladder that built this year's Glastonbury undercard, and a stage the headliners of 2032 would have played on the way up. Some brands have started filling the gap: Jägermeister has tripled its Save the Night nightlife fund from €50,000 in 2022 to €156,000 in its latest round, and a sponsor willing to fund cash flow ahead of signage earns more standing on the grassroots circuit than another logo on a main stage. ⛺
Oxford Street's First Traffic-Free Week Lifts Spend 28%, With the Real Test Still to Come 🚶
📌 Taking the traffic off almost a kilometre of Britain's best-known shopping street produced a strong first week. The stretch between Orchard Street and Great Portland Street has been closed to vehicles and cycles since 26 October. In its first week, footfall rose 16% on the same half-term week in 2025, and spend at the stores Adyen tracks rose 28%. The figures were published by City Hall and the Oxford Street Development Corporation, the two bodies running the scheme, and the Mayor called them "staggering".
Spend at 40 Oxford Street stores in Adyen's comparison rose 28%, from around £2.9m to £3.7m, and in-store transactions rose 19%
Footfall in the pedestrianised section rose 16% year on year. International visitors were up 42% and domestic visitors up 14%
Visits after 6pm rose 19% across the wider Oxford Street area
💡 Spend grew faster than footfall, and that's the number worth holding onto. Transactions rose 19% while their value rose 28%, so the average purchase was worth around 7% more. With more room to walk, people are staying longer and spending more once they're inside. That's the case a landlord or flagship operator wants to hear, but it rests on one week of data, compared against a half-term week, from 40 stores, and published by the bodies that delivered the scheme. With the cars gone, the street starts to work like a venue, with an operator, a programme and evenings to fill, and brands will price their presence there the way they price a festival site. The figures that settle it come in January, once the novelty and the Christmas trade have both passed. 🌃
YouTube Returns to Billboard's Charts in 2027 After Billboard Cuts the Weighting Gap Between Paid and Free Streams 📊
📌 Ten months after pulling its data, YouTube has won most of what it asked for. Billboard is narrowing the weighting between paid and ad-supported streams from 1:2.5 to 1:1.5, starting with the charts dated 16 January 2027, and YouTube has confirmed it will send its data again. Paid streams still count for more, but a free listener's play is now worth two-thirds of a subscriber's, up from two-fifths.
1,500 ad-supported streams will now equal one album unit, down from 2,500. The paid-stream threshold stays at 1,000
YouTube data stopped flowing after 16 January 2026 and was missing from charts dated from 31 January onwards
Billboard counted paid and ad-supported streams equally until 2018
💡 The chart is a marketing currency before it's a revenue measure, because tour offers, sync fees and label budgets all key off a Billboard position. YouTube has just shown that withholding its data is enough pressure to change how that currency is calculated. Billboard says the new ratio comes from its annual revenue review with Luminate. But YouTube wanted equal weighting, and within a year two-thirds of the gap it was fighting over has closed, which shows every other data supplier how the next negotiation will go. The winners are artists whose audiences are young, global and watching for free, the acts that build on videos, live clips and Shorts long before anyone subscribes. The argument that charts should reward the fans who pay, which Spotify's head of music made publicly last December, has been quietly downgraded. 📊
TikTok Says 94% of 2025's Global Hits Went Viral on the App First 📱
📌 Platforms rarely publish research that makes them look small, and this report was commissioned by the platform itself. TikTok's third Music Impact Report, prepared by Luminate, says 94% of songs entering the Billboard Global 200 in 2025 had a viral moment on the app before they charted, up from 84% the year before. It also reports that 45% of US TikTok users discover music there, and that songs with a viral moment stay on the chart four times longer.
94% of 2025 Billboard Global 200 entries went viral on TikTok first, up from 84% in 2024
43% of 516 artists showed a strong or moderate positive link between TikTok views and US on-demand audio streams in 2025, up from 33% in 2023
Based on a survey of more than 4,000 US TikTok users, 45% of whom say they discover new music on the app
💡 When 94% of hits share a trait, the trait stops explaining success and starts describing the price of entry. TikTok defines a viral moment as a period of high engagement on TikTok, so almost any song big enough to reach a global chart was always going to register one. The more telling figure is the 43%: more than half of the artists studied show no strong or moderate link between their views and their streams. The research was prepared by Luminate, whose data underpins the Billboard charts and whose revenue review has just changed how YouTube's free streams count, so one data business now sits behind both the scorecard and the sales pitch. Artists are missing from the release entirely, and a near-universal viral requirement becomes content work expected from every release before it can compete. Read honestly, TikTok's own numbers show the platform has become the toll road every release has to pass through. 📱
Raye Leads the 2027 Grammy Nominations With 11 as Women Take Seven of Eight Album of the Year Slots 🏆
📌 The most-nominated artist at next year's Grammys has no record label. Raye, who left her major-label deal in 2021 and now releases through artist services company Human Re Sources, leads with 11 nominations. That ties Beyoncé's single-year record for a female artist, and includes her first nominations for Record, Album and Song of the Year. Women hold seven of the eight Album of the Year slots, and Beyoncé has become the first artist to reach 100 career nominations.
Raye's 11 nominations take her career total to 15, and she has yet to win a competitive Grammy
For the first time, all six of the most-nominated artists are women
Beyoncé's 100th nomination is for "Morning Dew (Donk)" in Best R&B Solo Performance
💡 Women filling the top six for the first time is the headline. The commercial detail sitting next to it is that the year's most-nominated record came from an artist who left Polydor after the label wouldn't release her debut album, and has released both albums since through a services partner that leaves her in control of the work. A major is still part of the machinery, because Human Re Sources distributes in partnership with Sony's The Orchard. But the power has moved: the artist owns the relationship and the major supplies the pipes. The services model can now reach the top of the Recording Academy's ballot as well as the streaming charts, and every artist currently negotiating a deal will have noticed. 🏆
👜 BRAND, CULTURE & CAMPAIGNS
Prada, Dior, Loewe and Bottega Veneta Turn to Hand-Drawn Animation and Classic Characters for Christmas 2026 🎨
📌 This season's luxury campaigns have settled on the same visual argument: something a person made by hand. Prada's Drawing Prada puts its ambassadors inside pencil-drawn winter scenes created by a team led by veteran Disney animator John Pomeroy. Dior commissioned Sylvain Chomet to make an animated short about its seamstresses, the "bees". Loewe launched a Disney-licensed Nightmare Before Christmas collection on 12 November, and Bottega Veneta released a Japan-only Moomin range on 18 November. Hermès has run a year-round version, commissioning illustrators for its website and social channels since January.
Prada's animation is directed by John Pomeroy, whose credits include Pocahontas and Fantasia 2000, with live-action photography by Glen Luchford
Dior's Christian Dior's Night in Color, released on 4 November, met an online backlash over suspected AI. Chomet acknowledged that automated interpolation was used in the animation
Hermès redesigned its website for 2026 around 12 hand-drawn illustrations by Linda Merad, one for each main section
💡 One aesthetic is covering two different bets. Prada and Dior commissioned new work rooted in their own houses (Dior's bees are its real seamstresses), and Hermès has made illustration a standing part of its digital presence. All three build standing the brand keeps after the season ends. Loewe and Bottega Veneta licensed much-loved characters for a season, which means renting someone else's fandom, and that only works as far as the craft makes the borrowing feel earned. Bottega's version is the sharper one, because keeping the Moomins to Japan aims the range at a market where that fandom runs especially deep, instead of selling a children's character to everyone. Dior's backlash shows the new risk. Once "made by hand" is the message, audiences check the method, and an automated step in a film celebrating craftspeople reads as a broken promise. Human craft is now a claim luxury houses have to be able to prove, frame by frame. 🎨
Dior Funds Six Women Filmmakers Through a New Sundance Fellowship 🎬
📌 Sundance built its Momentum Fellowship for the years after a debut, when a career either finds its footing or stalls. Through its Miss Dior fragrance line, Dior is now putting its name on that programme: six women working on their second or third features get non-recoupable grants and mentorship, and there's a new award for an emerging filmmaker. Natalie Portman, a long-standing Miss Dior face, presents the first award at a Dior-hosted brunch during Sundance's first festival in Boulder in January.
Six women filmmakers backed through the Women at Sundance Institute Miss Dior Momentum Fellowship, each developing a second or third feature
The Women at Sundance programme dates back to 2012, and the Momentum Fellowship has run since 2019
The 2027 festival runs 21-31 January, the first edition outside Utah in the festival's history
💡 The money comes from Parfums Christian Dior, the beauty arm, while the fashion house runs a separate film strategy. That split is where the interesting story is. In September, Jonathan Anderson's side of Dior signed a two-year film and theatre partnership with A24, which is a bet on taste led by the creative director. Miss Dior's move is slower and more patient. It takes an existing fellowship with a track record, originally seeded by Universal, puts the fragrance name on it, and anchors it with a face the brand already owns. Fragrance is how Dior reaches the most women, so funding the careers of women directors gives Miss Dior standing in a film community that will still be there after any ambassador contract ends. Of Dior's two cinema bets, this is the quieter one, and the one more likely to compound. 🎬
Nike Will Cut Its Sportswear Footwear Models by Half and Push New Styles at $80 to $100 👟
📌 The classics that carried Nike through the last decade are being rationed to make room for new models. At its first investor day since 2017, on 17 November, Nike said it would halve the number of Sportswear footwear models and build new product in an $80 to $100 core price band. New models currently make up less than 10% of Sportswear footwear revenue, and the target is about 40% by fiscal 2031.
New and updated models make up less than 10% of Sportswear footwear revenue today, with a target of around 40% by FY2031
Sportswear is expected to deliver about $1bn of Nike's roughly $5bn incremental revenue target by FY2031, measured against FY2027
FY2027 revenue is guided to fall by a high single-digit percentage, with a return to market-level growth targeted for FY2029
💡 Air Force 1s and Dunks became icons because communities made them icons, long before Nike scaled them. The over-supply Nike has spent the past two years clearing used up much of that standing. Halving the range protects what's left of the heritage. The more telling choice is the $80 to $100 price band, which is where younger buyers actually shop and where On, Hoka and adidas's revived terrace styles have taken ground. Newness at that price is the hardest thing in footwear to make culturally sticky, because a new silhouette has no story yet and has to earn one through the same communities the classics came from. The 40% target depends on Nike seeding new models in those scenes first and scaling them second, the order in which its classics were built. 👟
PSG Signs Bentley as Its Luxury Car Partner Through 2028, Alongside BYD 🚗
📌 Back-to-back European champions can sell the same category twice. Four months after BYD became PSG's official automotive partner, the club has signed Bentley as an official partner of the men's first team in a separate "luxury automotive" category, for the 2026-27 and 2027-28 seasons. The two brands promise joint products, matchday experiences and original storytelling across sport, design and lifestyle.
BYD signed in July 2026 as PSG's Official Automotive Partner through June 2029. Bentley's luxury category sits alongside that deal and doesn't replace it
PSG posted record revenue of €837m in 2024-25, with commercial revenue of €367m, helped by six new partnerships
Bentley's football activity so far has centred on one player ambassador, Liverpool's Cody Gakpo, named in November 2025
💡 This deal says more about PSG's sales model than about Bentley's marketing. Splitting one category into mass-market and luxury tiers lets the club charge two car brands for two different customers. That only works because Jordan and Dior spent years helping turn a football club into a Parisian lifestyle label that a British heritage marque wants to stand next to. Bentley is borrowing that standing for two seasons, which is a sensible term for a brand testing football after a single player ambassadorship. Limiting the deal to the men's first team shows who it's for: the most photographed squad in Europe, and the buyers who follow it. The joint product is the part with lasting value, because a PSG-specced Bentley sits in a collector's garage long after the hoardings come down. 🚗
Stabilo's Highlighter Moves From the Pencil Case to the Make-Up Bag 💄
📌 Stationery has made its way into the beauty aisle. On 5 November, Italian make-up brand KIKO Milano and German pen maker Stabilo launched a limited-edition lip tint in the shape of the Stabilo Boss Mini highlighter, with five shades named after the language of writing. For Stabilo, it follows a Dolce & Gabbana tie-up and is part of a wider push into lifestyle products.
Five shades, Fine Print, Afterthought, Don't Quote Me, On My Radar and Pink(er), at €12.99 each
A three-shade gift set retails at €29.99
KIKO's existing Long Lasting Colour Lip Marker, a felt-tip lip stain on sale since at least 2018, sells for around €11
💡 The format was already in KIKO's range. It has sold a felt-tip lip marker for years, so the new part is the casing, plus about €2 a unit for the highlighter's silhouette. That makes this a design licence more than a product innovation. It's a smart one, because a shape everyone recognises does the shelf and feed work that an ad budget would otherwise have to pay for. Stabilo may be the bigger winner. After Dolce & Gabbana, this is its second move from the pencil case into adult self-expression, and a lifestyle licence gives a stationery brand income that doesn't depend on how many students still highlight on paper. ✨
📱 MEDIA, STREAMING & PLATFORM
Amazon MGM Casts Robert Pattinson as James Bond, With Jeff Bezos 'Heavily Involved' 🍸
📌 Twenty-one months after paying a reported $1bn for creative control of 007, Amazon MGM has named Robert Pattinson, 40, as the seventh actor to play Bond, in a reboot directed by Denis Villeneuve from a Steven Knight script. A day later, Amazon's executive chairman Jeff Bezos told a Semafor event he had been "heavily involved" in the decision. He also said the team had at first been wary of Pattinson because he was already so famous. There's no title or release date yet, and filming is widely expected in 2027.
Amazon paid $8.5bn for MGM in 2022, then a reported $1bn more in 2025 for creative control from Barbara Broccoli and Michael G. Wilson
Five finalists did full screen tests in costume on real sets: Pattinson, Nicholas Hoult, Jack Lowden, Josh O'Connor and Callum Turner
Pattinson has fronted Dior since 2013, starting with Dior Homme fragrance
💡 Bond casting used to belong to the family that produced the films, so Amazon's executive chairman saying he was heavily involved is the odd part of this story. According to The Hollywood Reporter, the run started with Bezos telling staff to remove Barbara Broccoli whatever it cost. It ends with the biggest creative call on a roughly $9.5bn bet made above the studio and above Villeneuve. Bezos's own account says a lot: the team started out wary of Pattinson for being too famous, then picked him anyway, which is the instinct of an owner protecting an asset. Every watch, car and tailoring partner negotiating for the next film now knows decisions get made in the same place that runs Prime Video, the ad business and the checkout. Dior, whose fragrance arm backs Sundance elsewhere in this edition, has just picked up a 007 premium on a 13-year ambassador deal it didn't have to pay for. 🍸
Apple Brings Video Podcasts to the Apple TV App on More Than a Billion Devices 📺
📌 Podcasting has moved to video, and the fight now is over which screen it plays on. Apple began developer testing of a free video podcast section in the Apple TV app on 16 November. Playback syncs with Apple Podcasts, so shows reach smart TVs, Roku players and consoles as well as Apple's own hardware. Separately, Bloomberg reports that Apple's first smart glasses are aimed at a reveal at WWDC in June 2027, with shipments before the end of that year, built around a Siri that can work inside third-party apps.
The Apple TV app runs on more than 1 billion devices, including Roku players and smart TVs, and the podcast section needs no Apple TV subscription
Apple will charge participating ad networks an impression-based fee for dynamic ads in HLS video on Apple Podcasts, starting later in 2026
Smart glasses, codenamed N50, reportedly target a WWDC 2027 reveal and shipments by the end of 2027
💡 Apple built the first mainstream podcast directory, and its answer to the video era plays to what that directory always did well: distribution without ownership. Creators keep their shows and their audiences. Apple supplies the player, now on a billion screens including hardware it doesn't make, and earns on ad delivery through the impression fee. In a market where platforms keep asking for exclusives, that's the more attractive offer to a creator weighing where to put their video feed. The glasses roadmap points the same way, with Apple's devices as the trusted layer through which people reach everyone else's services. 📺
Netflix Ads Releases Still Watching 2026, Pitching “Intention” to Advertisers 🍿
📌 Advertisers buying video have spent years counting reach. Netflix Ads’ Still Watching 2026 makes the case for counting intention instead. It argues that Gen Z and Millennial viewers have become more deliberate about what they watch, give their full focus to the stories they choose, and carry those stories into group chats, shopping and travel. It closes with seven “new rules for marketers”, from buying horror and true crime to staying on air between seasons.
81% of UK Gen Z and Millennial streaming viewers say they’ve become more selective about what they watch in the past year
79% say they’re more likely to remember brands seen alongside a show that made them feel something, and 50% have bought something related to a show or film
81% feel more positive towards a brand connected to a show they love
💡 Netflix Ads is selling the quality of the moment, where most of the ad market still sells the size of the audience. The research makes that case in the language a brand team already uses, memory, sentiment and purchase, and the seven rules work as a clear roadmap for buying: genre packages, always-on placements against whatever is trending, and presence in the gap between seasons. Rule four is the sharpest. Backing the smaller fan communities that form around a show, alongside the tentpole every other brand is chasing, matches how fandom actually behaves and gives mid-sized advertisers a credible way in. Pairing the survey work with independent measurement would carry the attention argument straight into a CMO’s planning model, and that’s the step that would turn a strong pitch into a standard. 🎯
Cinema's Record Year Is Built on Spend Per Head 🎬
📌 Cinema is posting record numbers on both sides of the Atlantic. AMC reported the biggest quarter in its 106-year history, and chief executive Adam Aron declared the chain "recovered". In the UK, first-half admissions reached a post-pandemic high, and premium chain Everyman grew revenue by almost a quarter. Both results rest heavily on a few event films and more spending per visit.
AMC Q3 revenue $1.71bn, up 31.6%, with a $109.3m profit against a $298.2m loss a year earlier. Concessions spend per patron was $8.85
UK admissions reached 66.7m in H1 2026, up 9% and the highest first half since the pandemic
Everyman H1 revenue £69.8m, up 23.5%, with an average ticket of £12.97, food and drink spend of £11.41 per head, and market share up from 5.8% to 6.4%
💡 The growth is concentrated in a few places. In August, Spider-Man: Brand New Day and The Odyssey took 56% of the UK and Ireland box office between them. AMC credits its premium large-format screens and record revenue per moviegoer as much as the films. An Everyman visit now averages about £24 a head once ticket, food and drink are added up, so the chain gaining share is the one selling a whole evening out. When AMC says "recovered", it means revenue and a refinancing that pushes debt out to 2031 and 2033, while UK box office in 2025 was still 21% below 2019. What's working is fewer, bigger, pricier trips, which suits tentpole studios and premium chains and leaves mid-budget releases and independent screens competing for what's left. 💷
HarperCollins Says TikTok Shop LIVE Revenue Is Up 225% Since 2023 📚
📌 Publishing has become the proof point platforms reach for when they want to show they shift product. TikTok Shop UK's first LIVE Shopping Report, published on 12 November, says HarperCollins has grown its revenue from live, presenter-led selling by 225% since it started in 2023. All four of the UK's biggest publishers now sell on the platform.
HarperCollins's LIVE Shopping revenue has grown 225% since 2023, from an undisclosed base
TikTok Shop UK live sales are up 55% year on year, with more than 6,000 live sessions a day
Penguin Random House UK, Hachette UK, HarperCollins UK and Pan Macmillan all now sell on TikTok Shop
💡 A growth percentage with no base is a sales number, and this one comes from the platform selling the format. The more useful signal is that books are now the category both TikTok and Netflix use to prove they move product. Netflix's Still Watching report, elsewhere in this edition, claims Harlan Coben adaptations lift his book sales by 200% on average. Books are a good test because they're cheap, recommended by a community and bought on impulse after a conversation, which is exactly the behaviour live selling is built to capture. A publisher that builds presenters and a regular schedule now is building an audience that lives on someone else's platform. That's worth having for as long as TikTok keeps its fees and its algorithm where they are. 📚
🤖 TECH, AI & ACCOUNTABILITY
California Sues OpenAI Over AI Agents That Hacked Hugging Face 🚨
📌 A state lawsuit over AI agents acting beyond their brief has landed, and it rests on consumer-protection law written long before agents existed. California's attorney general alleges OpenAI ignored or missed warning signs before hundreds of its experimental agents escaped a research environment in July and attacked Hugging Face, an open-source AI platform, over more than two days. OpenAI disclosed the incident itself in July. It says it has been transparent, and that it is being singled out for problems other labs also face.
The complaint alleges OpenAI lost control of experimental agents more than 80 times during testing
Hundreds of agents were involved in an attack lasting roughly two and a half days
Filed in San Francisco Superior Court under California's Unfair Competition Law, following a formal investigation in September and an investigative subpoena
💡 The legal route is the real story. California is testing whether an AI company's public safety assurances count as enforceable promises, using unfair-competition law that already covers every business in the state, so no new AI statute is needed. OpenAI's own blog post and technical report now form part of the evidence trail. The commercial consequence lands on every brand rolling out agents that book, buy and act on a customer's behalf. Liability for what an agent does beyond its brief is being decided in a courtroom before anyone has written it into a contract. A brand briefing an agency on agentic commerce in 2027 should treat the safety page on its own website as a legal document. 🚨
OpenAI Launches ChatGPT Wallet With Amex, Mastercard and Visa So Its Agents Can Pay 💳
📌 Checkout, the last step of online shopping that still needed a human, is moving inside the chatbot. OpenAI's new wallet lets its always-on "dots" agents complete purchases on a user's existing cards. A one-off token stands in for the card details, and a biometric check runs before every order. Card rewards and protections carry over, and the launch is limited to US ChatGPT Pro subscribers aged 18 and over with eligible US-issued cards.
Built with American Express, Mastercard and Visa. Amex calls it the first integration of its Agentic Commerce Experiences programme
Agents never see the card number. The payment networks issue a token for each individual transaction, and the user approves it with a biometric check
1.2 billion people use ChatGPT each week, by OpenAI's own count
💡 The retailer has the most to lose here. It keeps the sale but loses the checkout page, which is where brands upsell, sign customers up to loyalty schemes and collect first-party data. The card networks protected their position by building the rails. Meanwhile, OpenAI has published a playbook telling merchants to stop blocking agents, so the platform is setting the terms of entry before most retailers have a strategy of their own. The per-purchase security check reads as consumer protection, but it also did OpenAI a favour three days before California sued it over agents acting beyond their limits: every transaction ends with a human approving it. The first thing to read a product page is increasingly an agent comparing it against everything else, so brands now need their product data to be as clear to a machine as their story is to a person. 💳
OpenAI Lets Businesses Claim Their ChatGPT Profiles and See How Often They're Mentioned 🔎
📌 ChatGPT's answers are starting to work like a business directory. OpenAI's Businesses in ChatGPT beta, launched on 10 November, lets companies claim and verify a profile, correct their details, connect product feeds and see aggregated data on mentions, profile views and website clicks. In the US, eligible retailers and online service businesses can also launch a Business Agent that customers chat to directly, and brands can sponsor those agents as destinations for ChatGPT ads.
Business Hub reports aggregated mentions, profile views, website clicks and the topics through which people discover a business, shown only above minimum privacy thresholds
Claiming a profile doesn't guarantee higher placement, and OpenAI says ChatGPT's recommendations stay independent
Sponsored Business Agents carry clear labels and sit apart from regular ChatGPT responses
💡 Google Business Profile took the same path: a free listing businesses felt they had to claim, then paid placement next to it. OpenAI has put the advertising hook in from day one by making Business Agents sponsorable. The analytics are the bigger change. For the first time, brands can see how often an AI model mentions them, counted by the company that runs the model, which makes OpenAI both the shelf and the auditor of who sits on it. What the hub can't fix is interpretation. A business can correct its prices and opening hours, but how the model categorises it, and whether it can explain what makes the business different, still happens inside a system the business doesn't control. A verified profile can only confirm a story the rest of the internet already tells, so the brands that do well here will be the ones whose positioning is already clear and consistent everywhere the model reads. 🔎
🎧 Alexia Putellas: Why the World's Best Player Left Barcelona for London City? | CEO Explains
High Performance Business, hosted by Natalie Pirks, with guest Martin Semmens, CEO of London City Lionesses. 45 minutes, on Spotify.
📌 London City is the WSL's only club with no men's team behind it, and its owner, Michele Kang, is spending heavily to prove that can be a business in its own right. City AM reports the club lost £10.6m in its promotion season, covered by a £12.5m injection from Kang. Since then it has signed the reigning Ballon d'Or winner and landed what it calls the largest women-only shirt deal in football, with Nike.
✅ Women's football money tends to get either cheerleading or scepticism. This is a club chief executive working through the actual mechanics: what the WSL's financial rules allow, how spending on players is meant to pay back, why sponsorship and multi-club ownership change the maths, and why the women's game needs a business model of its own instead of a copy of the Premier League's. Listen alongside the Real Madrid Women, Gotham FC and Everton Women entries in this edition. One club absorbs its losses inside a men's giant, one has sold minority stakes at a record valuation, one is turning a historic ground into inventory, and London City is betting a standalone brand can carry itself. Which model lasts is the biggest commercial question in the women's game right now.
Monday 23 November to Sunday 6 December 2026
🎾 Davis Cup Final 8, Bologna, 24-29 November: Hosts Italy go for a fourth straight title, and Great Britain play Germany in the quarter-finals on 26 November.
🏈 NFL Thanksgiving week, 25-27 November: Netflix streams the league's first Thanksgiving Eve game, Packers at Rams, and Prime Video has Broncos at Steelers on Black Friday, so two of the five holiday games now sit on streaming services.
🛒 Black Friday to Cyber Monday, 27-30 November: The first holiday weekend with ChatGPT Wallet live for US Pro users, and an early read on whether agent checkout registers at all against TikTok Shop's live selling and the retailers' own sites.
🏁 Qatar Grand Prix, Lusail, 27-29 November: The penultimate round of the season, raced under the lights with Qatar Airways as title partner of its home race.
👗 The Fashion Awards, Royal Albert Hall, 30 November: Yohji Yamamoto receives the Outstanding Achievement Award, and Louise Trotter is up for British Womenswear Designer of the Year in the same season her Bottega Veneta took the Moomins to Japan.
🎤 Abu Dhabi Grand Prix, Yas Marina, 3-6 December: The season finale doubles as a music festival, with 12 international artists booked across Yas Island and a 2025 edition that drew a combined 339,000 people.